A small wholesale business has enjoyed a good year. Orders are steady, a major customer buys regularly, and the owner has invested in more stock in anticipation of continued demand.
Then circumstances change. The major customer delays payment. Suppliers increase their prices, and transport costs rise. At the same time, another customer reduces their orders.
The business still has products to sell and customers to serve, but money is tight. The owner must now decide which bills to pay first, how much stock to reorder and whether the business can meet its obligations.
The problem did not begin when conditions changed. It began earlier, when the business became too dependent on a few assumptions about what would happen next.
Uncertainty is part of running a business. The objective is not to predict every disruption. It is to build a business that can respond when reality differs from the plan.
What Does Business Resilience Really Mean?
Business resilience is the ability to withstand setbacks, adapt to changing conditions and continue operating through difficult periods.
For SMEs, uncertainty can take many forms: rising input costs, delayed customer payments, changing demand, supplier problems, new competitors or the loss of a major contract.
A resilient business does not necessarily have large reserves or access to unlimited funding. It understands its risks, monitors its financial position and has options when circumstances change.
That resilience is built through everyday decisions, long before a crisis arrives.
Five Ways to Make Your Business More Resilient
1. Know Your Cash Flow Before You Need the Money
Profit and cash are not the same thing. A business can make sales on credit and record revenue while waiting weeks or months to receive payment.
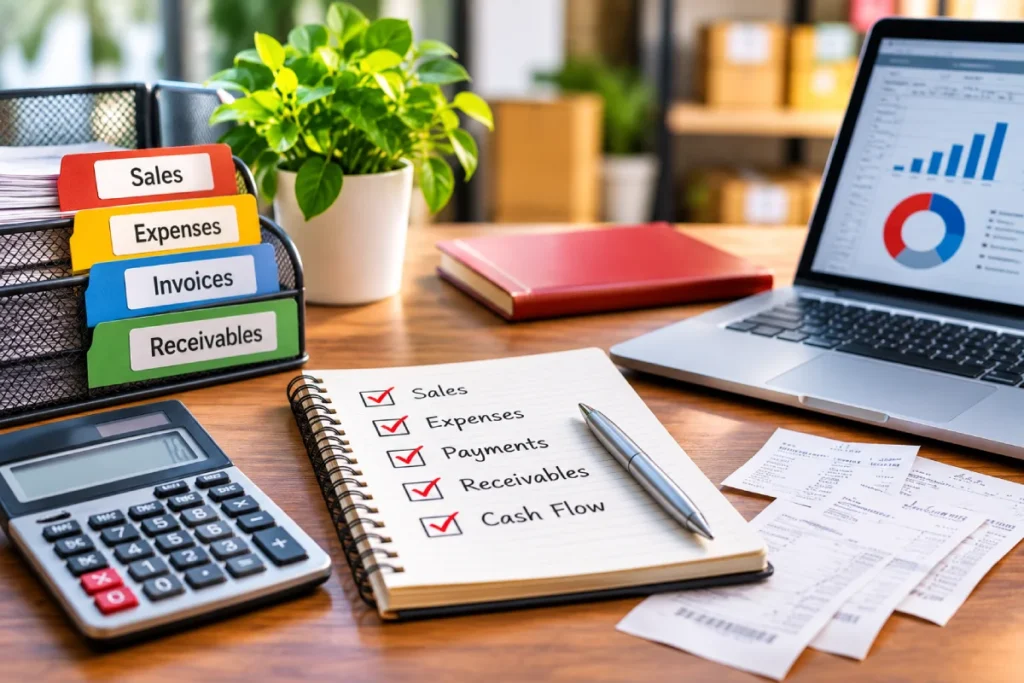
Monitor expected inflows, payment deadlines, recurring expenses and outstanding invoices. Prepare a simple cash flow forecast and update it regularly.
It is also useful to test different scenarios. What happens if your biggest customer pays late? What if supplier prices rise by 15 per cent? Can you still cover essential expenses?
Knowing the answers early gives you more time to act.
2. Avoid Depending Too Heavily on One Customer or Supplier
A major customer can be valuable, but relying on that customer for most of your revenue creates risk. The same applies when one supplier controls access to an essential product or material.
Where practical, develop relationships with additional customers and identify alternative suppliers. Diversification takes time, but it can reduce the impact of losing a critical business relationship.
The goal is not to abandon reliable partners. It is to avoid having no workable alternative.
3. Separate Essential Costs From Flexible Spending
Not every expense has the same importance. Rent, essential salaries and critical inventory may be necessary to keep the business operating, while some discretionary purchases or campaigns can be delayed.
Understand which costs are fixed, which vary with sales and which can be adjusted without damaging the business.
This makes it easier to respond to a downturn without making rushed decisions that create larger problems later.
4. Build a Financial Buffer Gradually
Unexpected costs are easier to manage when the business has money set aside for them.
If possible, establish a dedicated business reserve and build it consistently. The appropriate amount depends on your operating costs, payment cycles, industry and exposure to risk.
If a reserve is not yet realistic, begin by identifying the most urgent financial vulnerabilities and creating a plan to reduce them. Avoid treating borrowed money as a substitute for a sustainable financial buffer.
5. Make Your Operations Adaptable
Resilience is not only about money. A business can become vulnerable when all its knowledge sits with one person, its processes are undocumented or it has no alternative way to serve customers.
Document essential procedures, maintain accurate records, cross-train team members where possible and consider backup arrangements for critical services.
Flexible operations allow a business to keep serving customers when a person, supplier, system or location becomes unavailable.
Prepare for More Than One Possible Future
Return to the wholesale business. If the owner had monitored cash flow more closely, developed additional customer relationships and identified alternative suppliers, the disruption might still have been difficult, but the business would have had more options.
That is the point of planning for uncertainty. It is not about assuming the worst. It is about avoiding dependence on everything going right.
Review your risks regularly, decide which problems would hurt your business most and identify the actions you can take now to reduce their impact.
Resilience starts with knowing where your business stands financially. UCEE Business Banking provides business banking tools for transactions, bulk payments, salaries, bills and statements, helping businesses manage important financial activities in one place. Review your cash flow regularly and make informed decisions before challenges arise.